
Most user segmentation models fail in finance.
Not because teams don’t understand users, but because they assume that knowledge naturally leads to action. In money decisions, that assumption breaks almost immediately.
People delay, hesitate, outsource conviction, or act without fully understanding what they’ve signed up for. Traditional demographic or lifestyle-based segmentation doesn’t explain this behaviour.
This article documents a practical attempt at segmenting finance users based on how decisions actually get made.
Why finance decisions behave differently
Across products like Insurance, Bonds, Fixed deposits, Credit cards, and payments, one pattern shows up repeatedly:
Some users understand the product but don’t act.
Others act without understanding the product fully.
This mismatch is structural, not accidental.
Money decisions carry:
Fear of irreversible loss
Long-term consequences
Social and emotional weight
As a result, learning and acting don’t progress in a straight line.
The two variables that matter most
While working across multiple live finance products, two variables consistently explained user behaviour better than any persona or demographic layer:
Product knowledge
How well the user understands the product, its risks, and its implications.Intent / experience
Whether the user has already taken action or used the product.
Once these two are known, most other attributes become secondary.
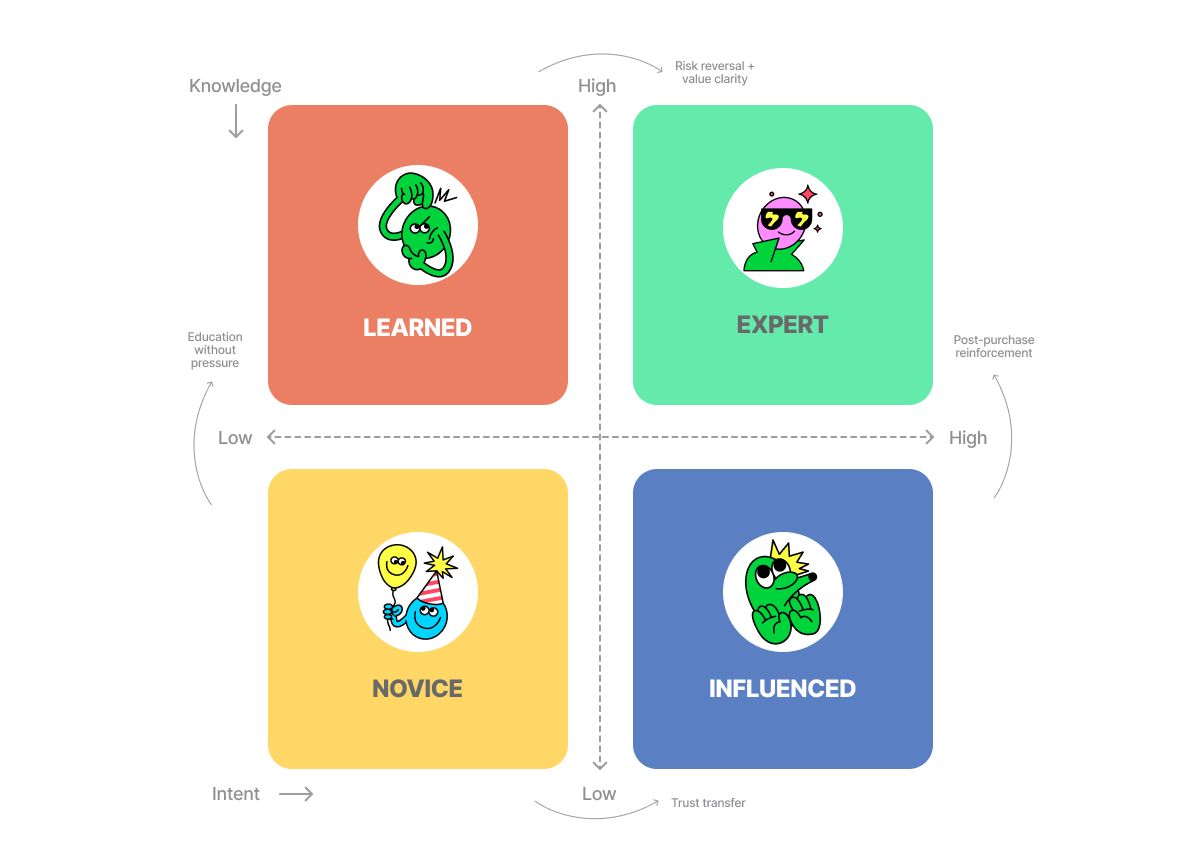
Mapping users on a 2×2 matrix
Plotting Product Knowledge against Intent / Experience results in four distinct user states.
These are not personas.
They are decision states — and users move between them.
Novice
Low knowledge · No Intent
This is the largest segment.
Users here:
Are unsure where to begin
Fear making a wrong decision
Feel overwhelmed by terminology and choice
More persuasion increases resistance.
What they need first is clarity without pressure.
Influenced
Low knowledge · High Intent
These users have taken action, but mostly on external conviction.
They:
Trust friends, advisors, influencers, or defaults
Struggle to explain what they bought
Feel uncertain after the transaction
The risk here isn’t acquisition — it’s regret and churn.
Post-purchase clarity matters more than pre-purchase persuasion.
Learned
High knowledge · Low Intent
This segment understands the product but hesitates to act.
They:
Compare extensively
Wait for the “right time”
Overestimate the risk of action
Additional education rarely helps.
What’s missing is confidence and risk mitigation.
Expert
High knowledge · High Intent
The smallest but most vocal group.
They:
Have real experience
Hold strong opinions
Influence others’ decisions
They don’t need guidance.
They need control, flexibility, and advanced tools.
Why movement matters more than classification
The value of this framework is not in labelling users.
It’s in understanding movement between states.
Most users start as Novices.
Very few become Experts.
Design and communication often fail because they assume users are already confident
Products fail because they design only for experts — and market to novices.
Each transition requires a different strategy:
Education without pressure
Trust reinforcement
Risk reversal
Enablement over explanation
Ignoring these transitions leads to drop-offs that no amount of optimisation can fix.
How this helps in practice
This framework helps teams:
Sequence information more effectively
Avoid premature persuasion
Design experiences that build decision confidence
Finance UX rarely fails because products are too complex.
It fails because decision states are ignored.