
AI adoption in fintech isn’t driven by how advanced the technology is.
It’s shaped by how AI behaves across a user’s financial journey.
People are generally open to AI. They already use it for explanations, summaries, and reassurance. But as soon as financial decisions start to feel serious — money involved, long-term impact, limited reversibility — expectations change.
Users slow down.
They want clarity.
They want to stay in control.
They don’t ask, “How smart is this AI?”
They ask, “Can I trust this when it matters?”
A shift in thinking
While thinking through AI in fintech, one shift became clear:
AI adoption isn’t driven by capability. It’s driven by behavior.
Users don’t evaluate models, features, or intelligence.
They evaluate how AI behaves as decisions move from low stakes to high stakes.
The principles below exist to manage that transition — to help AI earn trust gradually, without rushing users or taking control away from them.
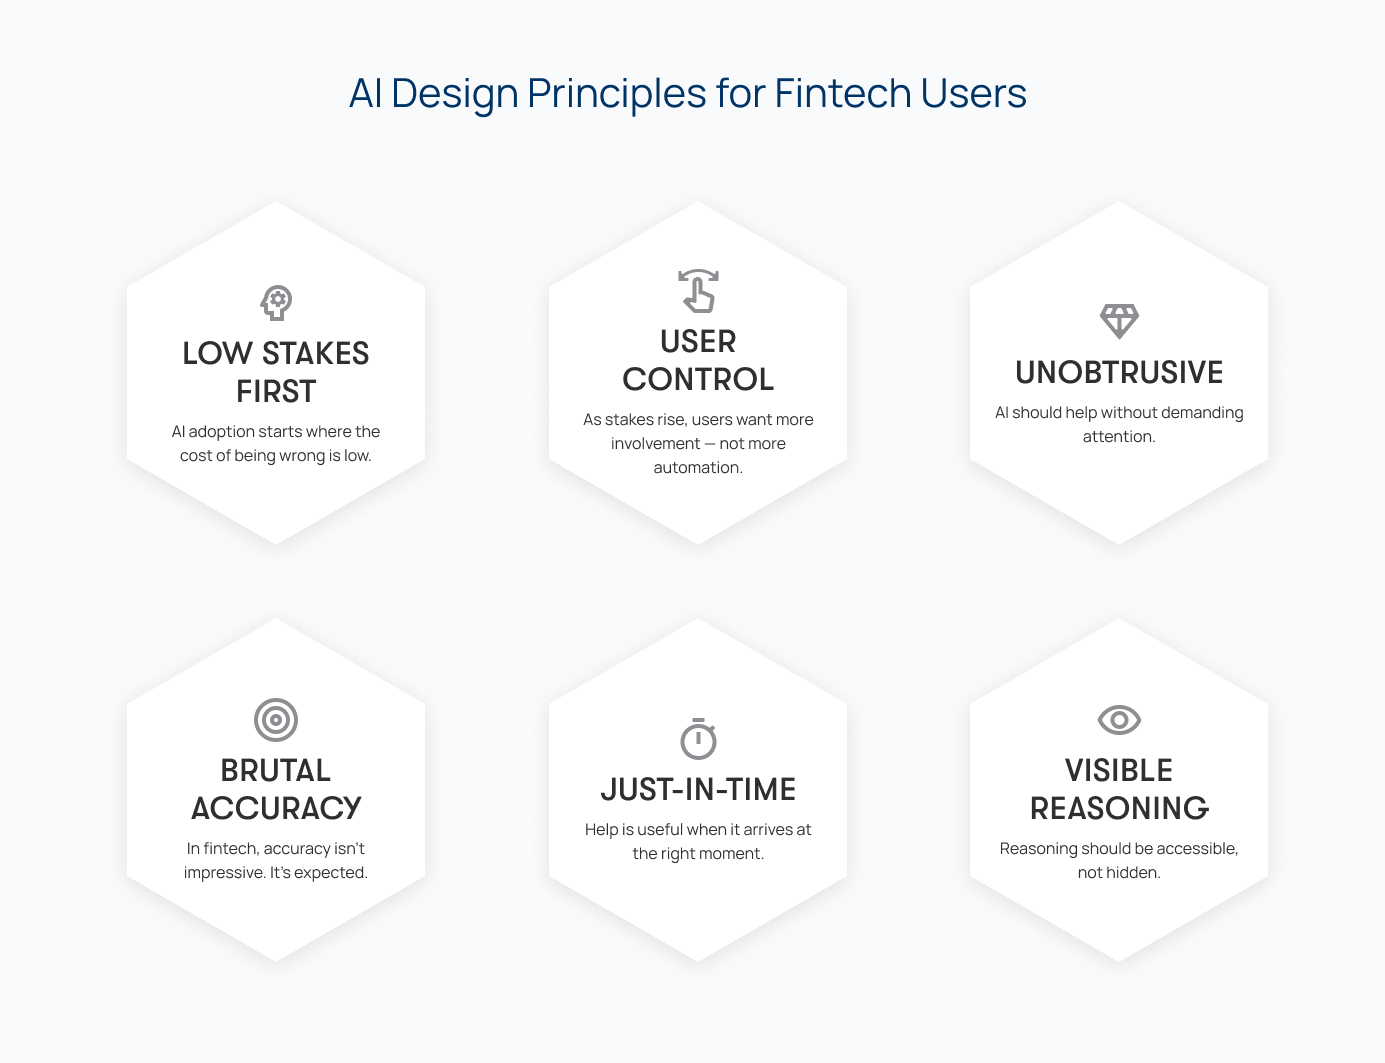
1. Low-Stakes First
AI adoption starts where the cost of being wrong is low.
When decisions are reversible, users are open to help. They explore. They experiment. They observe how the system behaves. That openness disappears once a decision feels final.
Design implication
AI should first show up as support, not judgment.
Where this works well
On an insurance or credit card detail page, AI can quietly summarise dense information into 2–3 plain-language points:
What this product is good for
One important trade-off
One thing users often overlook
While filling long forms, AI can replace static help text with contextual explanations that appear only when needed — explaining jargon or clarifying why a specific input matters at that moment
These moments don’t ask users to trust outcomes.
They help users trust understanding.
That’s how adoption begins.
2. User Control
As stakes rise, users want more involvement — not more automation.
High-impact financial decisions trigger caution. People want to explore options, compare trade-offs, and feel confident they weren’t rushed or overridden.
Design implication
AI should assist thinking, not replace it.
Where this works well
Quick comparison entry points where AI surfaces a short list of relevant options but lets users tweak priorities
AI-picked recommendation tags that are clickable — explaining why they were suggested and what influenced them
AI widgets with chip-based questions users can choose from during complex flows, instead of typing from scratch
Control builds confidence.
Confidence sustains adoption in high-stake moments.
3. Unobtrusiveness
AI should help without demanding attention.
Constant prompts, aggressive suggestions, or over-eager assistants create resistance. Intelligence that announces itself too loudly quickly loses credibility.
Design implication
AI should be present, but restrained.
Where this works well
A floating AI entry point that appears only after a period of hesitation or inactivity
Subtle micro-animations that signal availability without interrupting flow
Pre-filled, optional questions that invite engagement instead of pushing it
Unobtrusive AI feels respectful — and respect matters in financial contexts.
4. Brutal Accuracy
In fintech, accuracy isn’t impressive. It’s expected.
Users may forgive slow systems.
They rarely forgive incorrect ones.
One wrong perception can undo all the trust built so far.
Design implication
AI must be honest about certainty.
Where this works well
Clearly stating when outputs are estimates
Acknowledging uncertainty instead of guessing
Avoiding overconfident language in high-risk situations
Being transparent about limits builds more trust than pretending to be right.
5. Just-in-Time
Help is useful when it arrives at the right moment.
Too early, and it feels intrusive.
Too late, and it feels frustrating.
Design implication
AI should appear when uncertainty appears.
Where this works well
When users pause longer than usual
When they revisit the same section repeatedly
When they hesitate before committing to an action
Well-timed, simple help often feels smarter than complex assistance delivered at the wrong moment.
6. Visible Reasoning
Users don’t need to understand how AI works.
They do need to understand why something is being suggested.
Design implication
Reasoning should be accessible, not hidden.
Where this works well
Recommendation labels that link to short explanations
Clear signals about assumptions, inputs, or constraints
Lightweight breakdowns instead of black-box outcomes
An understandable answer beats a clever one in finance.
How these principles work together
These principles don’t work in isolation.
Trust built in low-stake moments carries forward only when AI stays unobtrusive, accurate, and well-timed as stakes increase.
Break one behavior, and adoption resets.
Together, these principles act as guardrails — shaping AI behaviour that users can grow comfortable with, from low stakes to high.
Conclusion
AI adoption in fintech doesn’t come from showcasing intelligence.
It comes from behaving responsibly.
The most effective AI experiences feel calm, restrained, and dependable — especially when the stakes are high.
That’s not a technology problem.
It’s a design responsibility.